Filing roofing insurance claims for storm damage in Smithville, MO gets a lot easier once you know the exact order of operations. Miss a step, like calling your insurer before a contractor ever sees the roof, and you can hand the adjuster an easy reason to lowball or deny the claim. This guide walks through each step in order, including one Missouri-specific legal detail most local contractor sites get wrong.
Why Smithville Homeowners File So Many Storm Damage Claims
Smithville sits inside the Kansas City metro's hail and wind corridor, and that geography shows up directly in claim volume. Hail alone accounts for as much as 80% of severe convective storm claims in any given year, with roofs bearing an estimated 70% to 90% of total insured residential catastrophic losses.
Regional data backs up what Clay County homeowners already know about spring and summer storm seasons. Neighboring Kansas counties alone logged hundreds of reported hail events in a single recent year, underscoring how active this part of the Midwest hail belt really is.
Our crews field calls across Smithville and Clay County after nearly every significant hail event, and the pattern repeats: the homes with a recent inspection on file settle faster than the ones scrambling for proof their roof was in good shape beforehand.
For a full record of storm activity in your area, the Storm Events Database contains records on various types of severe weather, as collected by NOAA's National Weather Service (NWS) , searchable by county and date. If you want to confirm your home sits in a covered service area, check the Smithville, MO service page.
Step 1: Assess the Damage Safely
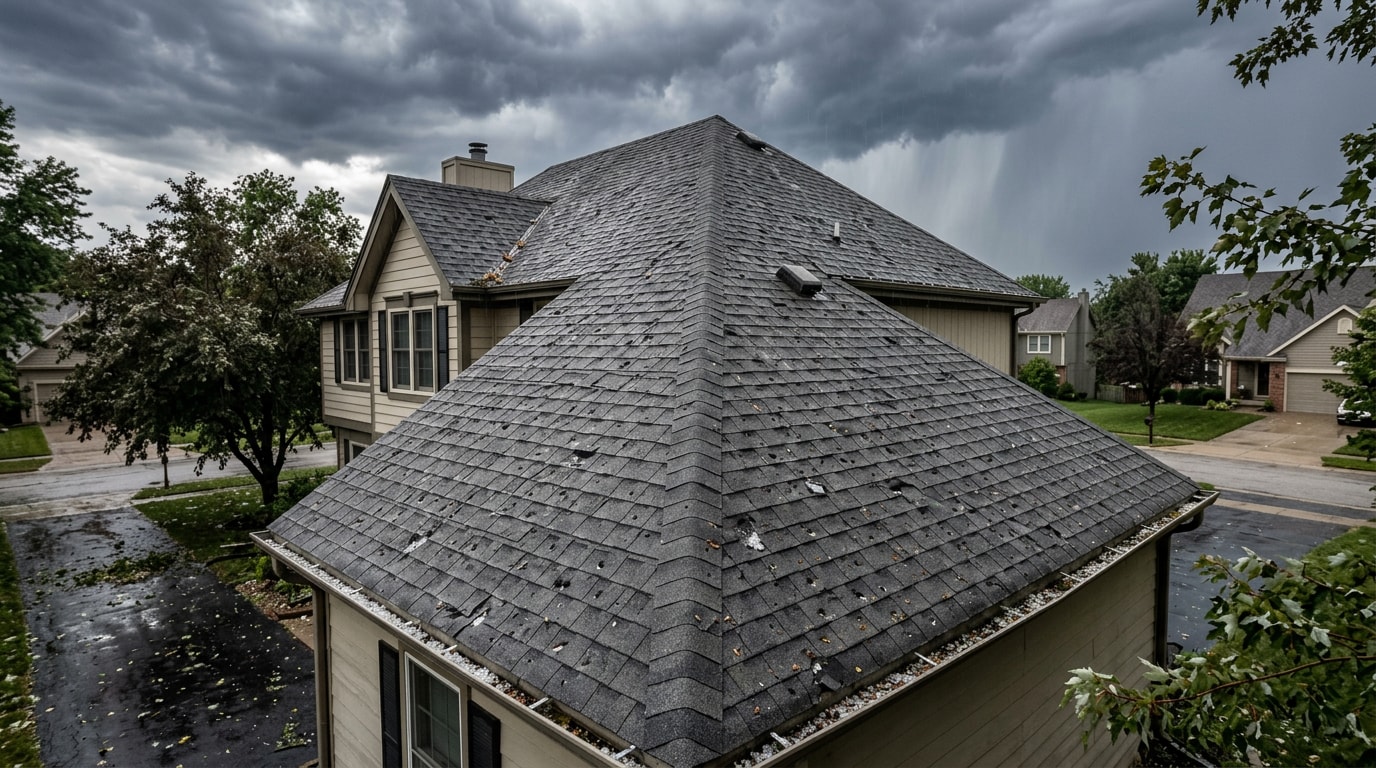
Start with a ground-level walk around the house. Do not get on the roof yourself.
Look for these signs:
- Missing, curled, or torn shingles
- Dented gutters, downspouts, or AC units
- Granules collecting in gutters or downspout runoff
- Daylight through the attic roof deck
- Fresh water stains on the attic ceiling or insulation
Document everything with timestamped photos and video from the ground. If you find an active leak, tarp it temporarily. Everything else can wait for a professional roof inspection after storm damage.
Step 2: Get a Professional Inspection Before You Call Your Insurer
A professional inspection before you contact your carrier protects you, because the adjuster who eventually shows up works for the company paying the claim, not for you.
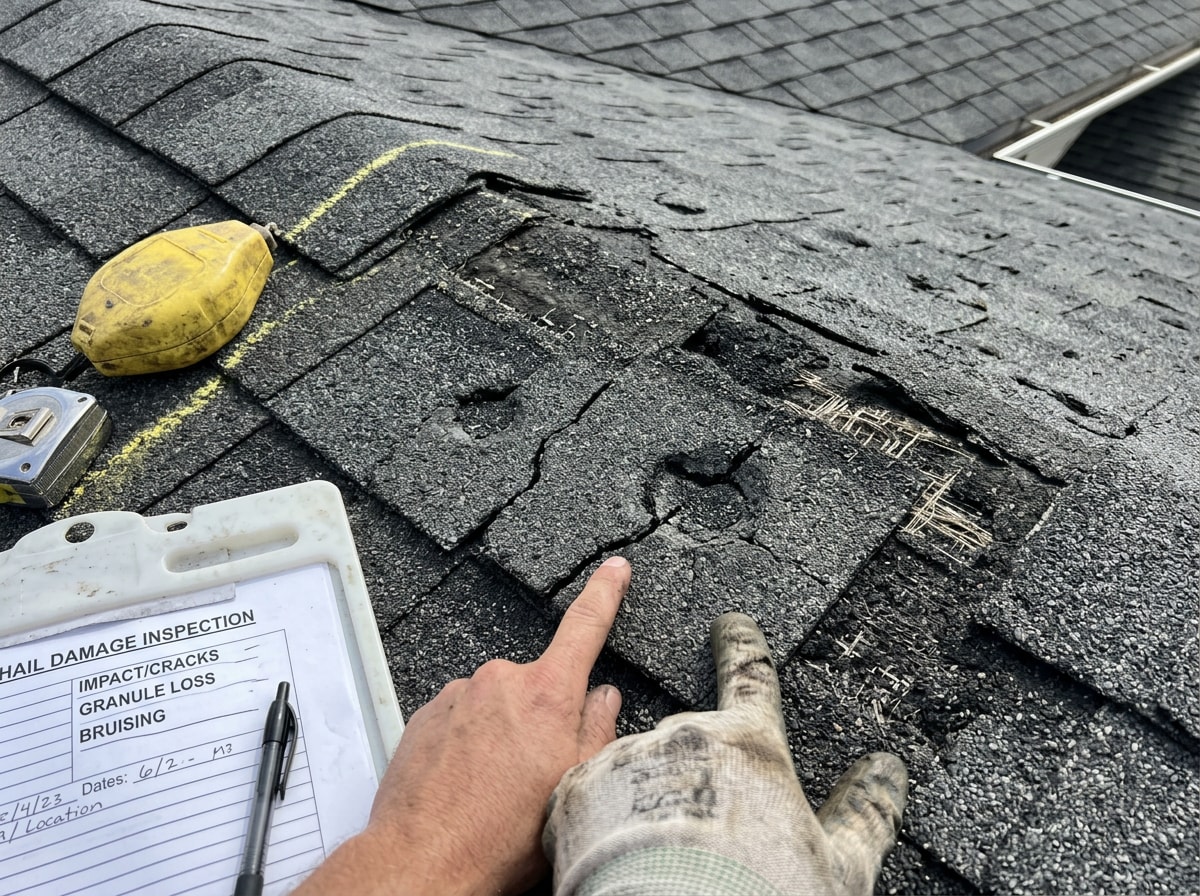
Hail damage often hides as subtle bruising on shingles or soft-metal flashing that a photo or drone pass simply will not catch. A manual, on-roof inspection lets a trained eye feel for soft spots and check metal components up close. Drone or photo-only inspections are faster and safer on steep roofs, but they typically miss granule loss patterns and bruised mat fibers that only show up under hands-on inspection.
Look for a contractor with HAAG training, which teaches inspectors to document hail impact density, strike diameter, and soft-metal evidence in a way that holds up against an insurer's own engineer. If you want that level of documentation before you file anything, start with a roof inspection.
Step 3: File Your Claim
Once you have documentation, file the claim with your carrier. You will need:
- Your policy number
- The date of the storm
- A written description of the damage
- Supporting photos or your inspector's report
Report the damage promptly. Most homeowner policies set their own reporting windows in the declarations page, separate from any broader contract statute of limitations, so check your policy rather than guessing at a deadline.
Step 4: The Adjuster Visit (And What Missouri Law Actually Allows)
During the adjuster visit, the insurer's representative climbs the roof, measures damage, and calculates repair costs using standard pricing software. That becomes the claim scope, the official list of what the insurer agrees to cover.
Most Smithville homeowners assume their contractor can simply "handle" the insurance company for them. That is not quite how Missouri law works, and getting this wrong can cost you a legitimate claim dispute later.
A contractor shall not represent or negotiate, or offer or advertise to represent or negotiate, on behalf of an owner or possessor of real estate on any insurance claim in connection with the repair or replacement of roof systems , under Missouri Revised Statute 407.725. Any violation of this section by a contractor shall be considered an unfair practice pursuant to the Missouri merchandising practices act.
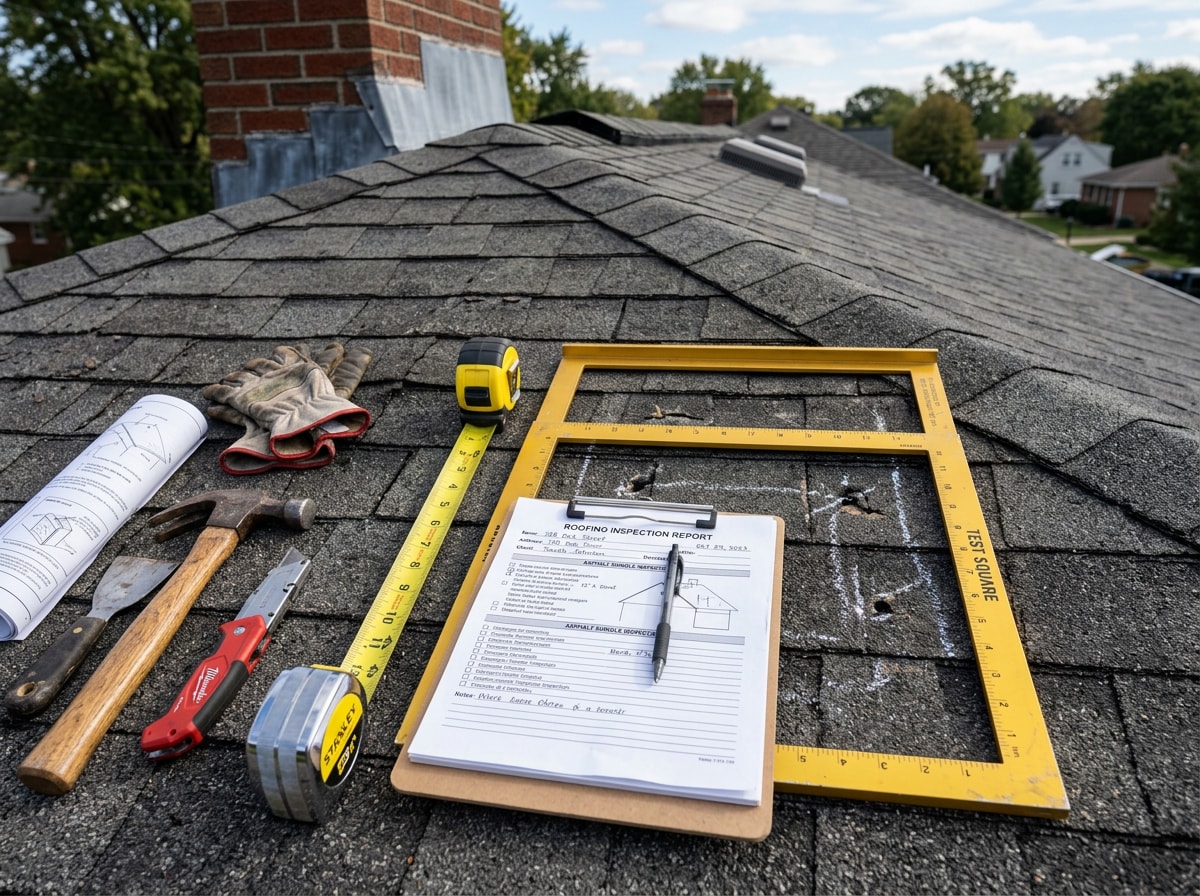
In plain terms: your contractor can walk the roof with the adjuster, point out hail bruising, soft decking, or damaged ridge caps, and provide a written inspection report. What your contractor cannot legally do is negotiate the dollar amount of your settlement on your behalf. That authority stays with you, the policyholder, or a licensed public adjuster you choose to hire. Knowing that distinction keeps you from relying on the wrong person to fight a denied or underpaid claim.
If you need support preparing documentation before that meeting, insurance claim roof assistance covers exactly that preparation work.
ACV vs. RCV: How Missouri Roof Claims Actually Get Paid
Most standard Missouri homeowner policies settle in two payments rather than one lump sum.
| Payment Type | What It Means | When You Receive It |
|---|---|---|
| Actual Cash Value (ACV) | Depreciated value of the damaged roof | Issued shortly after the claim is approved |
| Recoverable Depreciation | The difference between ACV and full replacement cost | Released after repairs are completed and invoices are submitted |
| Replacement Cost Value (RCV) | ACV + recoverable depreciation combined | Total amount paid once the job is finished |
If your contractor never submits a completion invoice, you leave the recoverable depreciation on the table. That paperwork step matters as much as the inspection itself.
Common Reasons Missouri Roof Claims Get Denied
These are general patterns insurers cite, not guarantees. Actual outcomes always depend on your specific policy's declarations page.
- Pre-existing damage the insurer argues predates the storm in question
- Improper maintenance, such as ignored leaks or deferred repairs
- Late reporting, filed well after the policy's required window
- Policy exclusions, including cosmetic hail clauses or roof age limits
Reading your exclusions section before a storm hits can save confusion later. If your claim was already denied or underpaid, a storm damage roof repair inspection can document missed damage for a reinspection request.
What to Look for in a Smithville Storm Damage Roofing Contractor
Understanding the claims process is only half the equation. The right contractor makes the difference between a smooth claim and a frustrating one.
Is the contractor actually based in Smithville? A local contractor with a verifiable address has a reputation to protect here, unlike out-of-town storm chasers who disappear after a season ends.
Do they carry HAAG training or equivalent inspection credentials? That training sets a consistent, defensible benchmark for telling storm damage apart from ordinary wear.
Will they attend the adjuster meeting? Even without the authority to negotiate your settlement, a contractor on the roof during the inspection can flag damage the adjuster's walkthrough misses.
Do they offer to waive your deductible?
A contractor shall not advertise or promise to pay or rebate all or any portion of any insurance deductible as an inducement to the sale of goods or services under Missouri law. Treat any contractor who offers this as a red flag, not a perk.
For a closer look at repair scope and typical costs once a claim is approved, the Residential Roof Repairs in Smithville, MO guide covers what homeowners usually pay out of pocket beyond the deductible.
Ready to get documentation started before you call your insurer? Get a free estimate and have a written inspection report in hand before the adjuster ever shows up.
FAQ
Can a roofing contractor help with storm damage or insurance claims?
Yes, within limits. A contractor can document damage, attend the adjuster meeting, and provide a written inspection report. Under Missouri law, however, a contractor cannot negotiate or represent your claim on your behalf; that right belongs to you or a licensed public adjuster.
Will my home insurance cover roof replacement?
Coverage depends on the cause. Storm, wind, and hail damage is typically covered, while age-related deterioration usually is not. Always check your policy's declarations page for specific exclusions and deductibles.
What should I do first after a hail storm in Smithville?
Inspect visible areas from the ground, check your attic for leaks, and document everything with photos. Then schedule a professional inspection before contacting your insurer about a potential claim.
Is it legal for a contractor to negotiate my insurance claim for me in Missouri?
No. Missouri Revised Statute 407.725 prohibits contractors from representing or negotiating an insurance claim on a homeowner's behalf. A contractor can be present and document damage, but the negotiation itself is yours to handle or to assign to a licensed public adjuster.
Can a Smithville roofing contractor help if my insurance claim was denied or underpaid?
Yes. A contractor can provide additional documentation and request a reinspection if the approved scope does not match the actual damage found on the roof. If the dispute does not resolve at that stage, you may file a complaint with the Missouri Department of Commerce and Insurance .
Will my insurance premiums go up if I file a storm damage claim?
It depends on your carrier and claims history. A single weather-related claim typically has less impact on renewal rates than claims tied to neglect or repeat losses, but policies and underwriting rules vary by insurer.
Questions about a specific claim situation? Visit Redemption Roofing USA or contact the team directly to schedule a documented inspection before your adjuster visit.